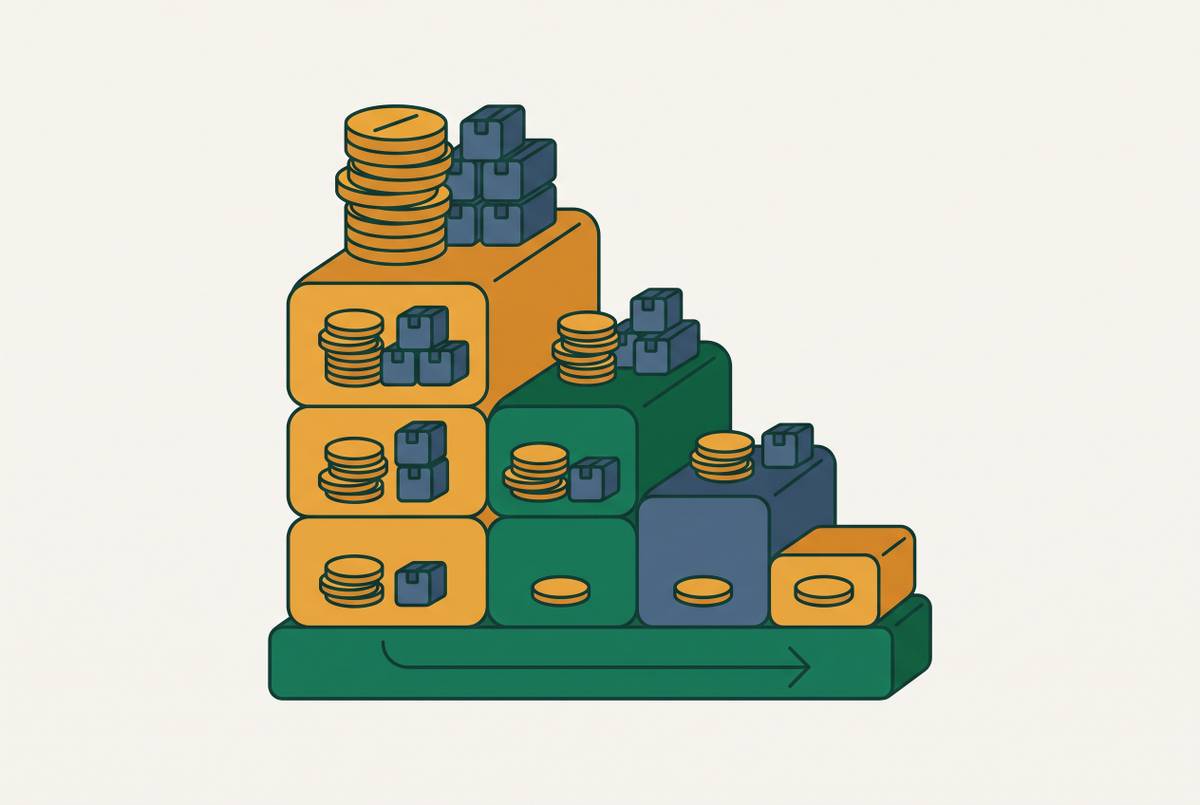
Credit Bundle Tier Architecture for SaaS Products
AI's variable costs forced SaaS to layer credits over usage tracking.
SaaS pricing has moved, within the space of a year, from seats to a two-layer system: a subscription or seat price on top, and a metered credit ledger underneath that actually tracks what things cost. That shift is a structural response to a cost problem AI introduced into software billing, and the same case files that document its rise also document how badly it can go wrong when nobody designs the layers underneath the credit on purpose.
Credit bundles: how SaaS pricing converged on them, and the new failure modes they created
Traditional software carried almost no marginal cost per user. AI changes that arithmetic completely. Every token processed, every model call, every tool invocation carries a real cost that moves with what the user actually does, so the old flat-fee logic no longer lines up with the vendor's expense line.
That mismatch breaks per-seat pricing in both directions at once. The pricingio.com 2026 guide documents how "unlimited AI" folded into a flat subscription can quietly erode gross margins, because the vendor has no mechanism to charge the heavy user more than the light one. The obvious fix, pure usage-based pricing, solves the margin mismatch but makes budgeting harder: enterprise procurement teams need a number to defend in a budget meeting, and a meter that bills whatever gets consumed gives them nothing to point to before the invoice arrives.
The credit bundle is the compromise that satisfies both constraints. It's a prepaid, abstract unit, and the buyer gets a number to budget against. A metered settlement layer tracks actual usage, so the vendor can recover its real costs. GitHub Copilot is the clearest case of this transition in practice: it moved from a fixed request allowance to a credit system where each credit maps to a defined amount of API usage, the seat price becomes the basis for a credit grant that can be worth more in dollar terms than the seat price itself, and actual consumption settles against published token rates.
Adoption of this model has outpaced the care put into building it. The same sources that chart its rise also document its casualties: bill shock, public apologies, mid-contract repricing, margin collapse. In every documented case, the credit abstraction itself was not the point of failure. The tier boundaries, the overage mechanics, the rollover rules, and the metering underneath were left to default behavior instead of deliberate design, and that is what customers actually ran into.
Designing the credit abstraction deliberately
A credit is not a measure of product value. It functions as an internal exchange rate dressed up as a customer-facing unit, and the rate a vendor sets between credits and underlying cost determines margin, perceived fairness, and how much leverage a customer gets in a renegotiation.
Because the vendor controls that exchange rate, it can set a different conversion for every feature, model tier, or action type. That flexibility opens the door to cross-subsidy: a feature with low token cost can carry a high credit price, and a feature with high token cost can carry a low one, with the blended result protecting the vendor's overall margin even though no individual transaction reflects its true cost. But this only works if the vendor keeps a separate record of what things actually cost underneath the credit count the customer sees. The QubitTool 2026 AI pricing guide shows this with an event schema in which the customer sees "8 credits" while finance and engineering see the exact input tokens, output tokens, and estimated dollar cost behind that number. A credit schema that collapses all of that into a single number loses the ability to re-rate past usage if the credit-to-dollar mapping ever changes, which matters the first time a vendor needs to adjust pricing without breaking every historical invoice.
Those incidents that triggered public apologies, Cursor's surprise overcharges and mid-contract repricing among them, all trace back to a mismatch between the credit contract the customer saw and the usage settlement that actually generated the bill, and that mismatch is possible only when the metering layer beneath the credit bundle fails to hold up under scrutiny. Avoiding that mismatch takes billing infrastructure built to keep customer-facing credits, internal cost tracking, and final invoices consistent within one system, rather than three separate spreadsheets reconciled by hand once a month.
The abstraction turns into a liability the moment a sophisticated buyer can see through it. When credits track published API token prices closely enough to be legible, an enterprise buyer can reverse-engineer the vendor's margin and negotiate directly against it, so the credit layer that was supposed to protect pricing becomes a transparency problem instead. That is close to what happened with Cursor: the new model referenced API rates directly, which stripped away the abstraction that had previously kept the price insulated from scrutiny. The credit-to-dollar rate needs to hold up as a value exchange: credits bought a unit of capability, a direct exchange rather than a markup stapled onto a token cost.
The choice of what a credit represents also shapes customer behavior long before any tier boundary gets drawn. Tokens are the right unit for tracking internal cost, but they rarely make sense as the thing a non-developer customer sees on their invoice. The QubitTool guide lists better customer-facing units: AI messages, documents processed, minutes transcribed, images analyzed, workflows completed. Intercom Fin is the clean example: it charges per resolution, per handoff, per disqualification, or per lead qualification, with one charge maximum per conversation, so the credit unit maps directly onto the outcome the customer actually values rather than onto the machinery behind it.
Setting tier boundaries that reflect actual consumption patterns rather than round numbers
Tier boundaries built from usage data produce tiers that match the way customers actually consume the product. But if you build tier boundaries from competitor benchmarking or a preference for round numbers, the tiers either trap customers below their real need or leave expansion revenue sitting on the table.
Consumption in AI products rarely spreads evenly across a customer base. A small share of power users can account for a disproportionate share of total credits consumed, and that skew means a tier boundary set at the median usage level will read as a hard ceiling to a meaningful minority of the customer base, even though it looks generous on paper. This is an empirical exercise.
The size of the gap between tiers carries as much weight as where any single boundary sits. A gap that is too wide forces a customer who needs only a little more headroom to buy an entire tier's worth of capacity they don't need. The right gap tracks a real jump in usage behavior between customer segments, applied deliberately rather than as a tidy percentage increase from one tier to the next.
Enterprise tiers run on different logic than SMB tiers. SMB limits need to cover the median heavy user in that segment without triggering overage, because small teams usually have no finance function in place, and no one catches a surprise charge before it becomes a problem. Enterprise tiers, by contrast, are frequently commit-based rather than capped: the customer buys a usage commitment up front, and the negotiation happens over the size of that commitment rather than the price of each unit. Salesforce Agentforce shows what that looks like in practice, offering buyers a choice between Flex Credits priced per action, a flat $2 per conversation, or an unlimited per-user monthly rate, which lets each enterprise customer pick the structure that fits how it actually uses the product instead of having the vendor impose one model on everyone.
Overage mechanics: why the design of what happens after a credit bundle runs out determines customer trust more than the bundle itself
Tier boundaries decide what's included. Overage mechanics decide what happens at the edge of that boundary, and the record shows that edge is where most bill-shock incidents actually start.
Cursor's June 2025 incident is the clearest documented case of overage design gone wrong. Users hit the limit of their $20 allowance in the middle of a session, the system kept billing at API rates without any visible interrupt, and for many customers the first sign anything had changed was an invoice they didn't expect. The failure here wasn't the pricing model Cursor chose. It was the absence of a customer-visible stop at the exact moment the boundary was crossed. Zylo's 2026 SaaS Management Index backs up how widespread this problem has become: a large majority of IT leaders reported unexpected charges tied to consumption or AI features, and the word doing the real work there is "unexpected," not the size of the bill. A high bill that arrived with no warning generates support tickets, refund demands, and the kind of public complaint that ends up in a CEO's apology post.
Three overage designs appear across the market, and each one carries a different trust and margin tradeoff. A hard stop halts usage the moment credits run out, so it eliminates bill shock entirely, but it interrupts a workflow mid-task, which is worse for a high-value enterprise job than for routine SMB usage. A negotiated overage rate, set in advance as part of an enterprise contract, removes the surprise even when it eventually triggers, because the price was known before any usage happened.
Whichever design a vendor picks, the price of overage credits has to sit above the price of bundle credits, and it can't read as a penalty. When bundle credits cost noticeably less per unit than overage credits, that gap signals to the customer that going over the bundle is meant to be the exception rather than the plan, which fits SMB pricing where the vendor wants customers to upgrade rather than live permanently in overage territory.
None of these mechanics matter as much as whether the customer can see consumption happening in real time. A customer who can watch usage climb against their bundle limit inside the product will self-manage: upgrading ahead of the cap, cutting back on lower-priority tasks, or requesting an add-on before the billing period closes. A customer with no visibility into usage in flight gets a surprise invoice regardless of what the contract said about overage pricing. That requirement sits with engineering, not with the billing page: real-time visibility depends on a metering system fast enough to aggregate and surface consumption as it happens, not merely fast enough to produce an accurate invoice at the end of the month.
Rollover rules and credit expiration, the structural decisions that determine whether a credit bundle feels fair
Credit expiration is one of the most consequential design choices a vendor makes, both legally and in terms of the customer relationship, and most teams arrive at a policy by default rather than by deliberate decision.
Unused credits that expire count as breakage, and under ASC 606, you have to recognize breakage on a defensible, documented pattern rather than let it sit indefinitely as deferred revenue on the balance sheet. That accounting rule creates a real incentive to expire credits on a fixed schedule, but that incentive has to be weighed against how customers experience the expiration. The successknocks.com report notes that its own recommendation to buyers is to demand rollover rights on unused credits before letting a pilot scale into a full contract, and vendors who build rollover in as a feature rather than an afterthought tend to win enterprise deals that rigid expiration policies lose.
Four rollover designs recur across the market, and each one carries its own consequences for margin, accounting, and how fair the arrangement feels to the customer. Paid rollover, where a vendor charges a small fee to carry credits past their normal expiration, turns what would otherwise be pure breakage into revenue, though customers can read it as being charged for not using the product.
Accounting treatment shapes rollover design without fully dictating it. Prepaid credits count as deferred revenue under ASC 606, and the vendor can only recognize that cash as revenue once the credits are actually consumed. Once a tier is live, if its boundaries or its overage rate change, the billing system has to apply the new terms going forward without disturbing past settlements or producing retroactive surprises on a customer's invoice. That's only possible if the metering and billing engine can isolate the moment a tier change takes effect and apply it at the point of contract amendment, rather than patching it in by hand at the end of the month. Getting the accounting right is necessary. It is not sufficient on its own to make a credit bundle feel fair to the person paying for it, and that is the standard every decision in this architecture, tier boundary, overage rule, rollover policy, ultimately has to meet.