Credit Package Design for B2B Team and Seat Contexts
Pooled team credits outperform per-seat models for most B2B use cases.
Credit packages in B2B software are having their moment, and most of the industry is making the same structural mistake: designing the balance for a single user, then bolting a team on top of it after the fact. The PricingSaaS 500 Index tracked more than 1,800 pricing and packaging changes across the top 500 B2B and AI companies in 2025, and credit models grew 126% year-on-year, from 35 companies to 79. Adoption sits at 29% today, with another 33% planning to roll out AI credits in the next six to twelve months. Pooling beats per-seat allocation for almost every team building this, and the companies still arguing otherwise are usually protecting a legacy billing system, not a better customer outcome.
The assumption baked into most credit systems from the start looks like this: one balance, one user, a burn rate you can predict, and a person to hold accountable when it runs dry. That model works fine for a single subscriber running a solo workflow. Add a second seat and the whole thing falls apart. Whose credits run out first? Does the power user on the team torch the shared balance before the light user even gets a chance to see the product work? And when the pool hits zero, who gets the bill: the seat, the team, or the admin who approved the plan?
Team use brings in variables that individual credit design never had to deal with: shared balances, role hierarchies, cost centers that want to see their own spending, and consumption that's wildly uneven across seats. None of this is an edge case. It's the default condition of B2B software, where hybrid pricing (some mix of subscription and usage-based charges) now shows up in 37% of software companies, according to Kyle Poyar's 2026 State of B2B Monetization survey of 230 companies. Pooling, allocation, rollover, and overage aren't cosmetic settings on a pricing page. They're the load-bearing structure underneath it, and built wrong, that structure creates friction and churn instead of the adoption and expansion it's supposed to drive.
How seat-based credit pools became the standard team packaging pattern
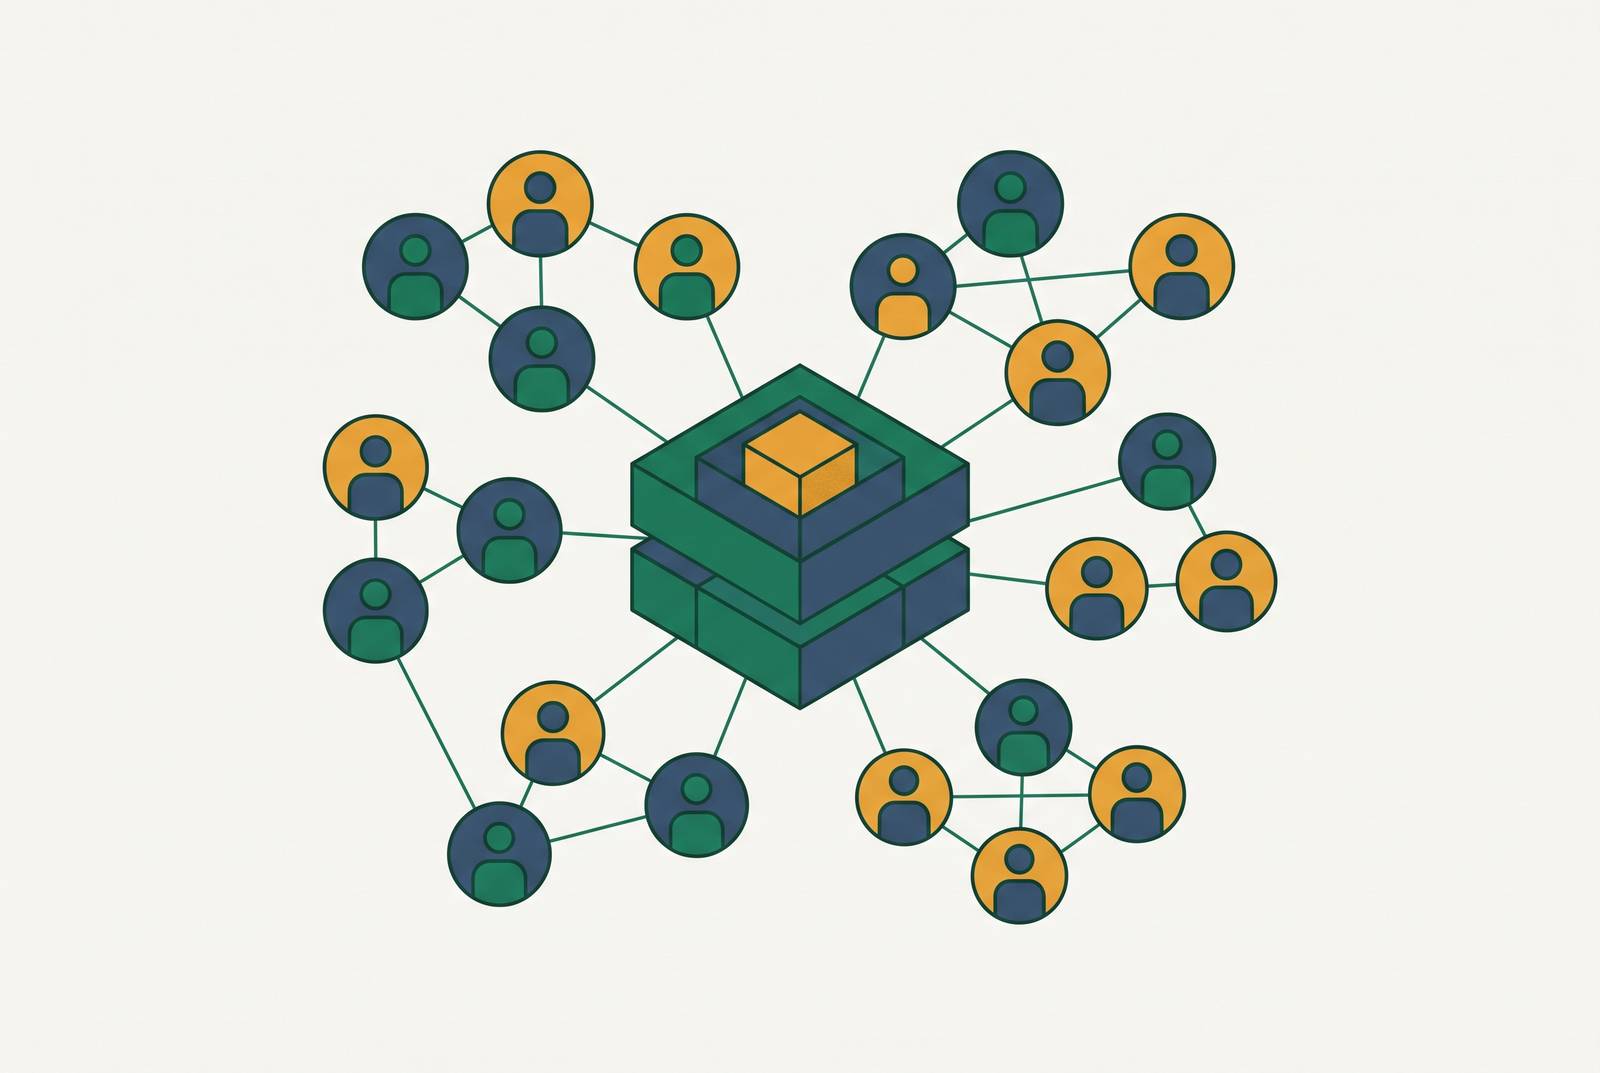
A seat-based credit pool works like this: each seat a company buys puts a fixed number of credits into one shared, account-level balance, and every user on the team draws from that same pool. Say a team buys 10 seats, and each seat contributes 100 AI credits a month. The team now has a shared pool of hundreds of credits that anyone on the account can pull from, regardless of who used what last week.
Pooling wins for most teams, and not for some soft cultural reason. It kills the "is my bucket empty" anxiety that makes individual users hoard credits instead of actually trying the product. It lets power users and early adopters burn through more of the pool without blocking teammates who are still figuring out whether the tool is worth their time. And it lowers the internal barrier to that first real adoption push, which is usually the thing that decides whether an account expands later.
Two other models still show up in the market, and each has a narrow, real use case, not a general one. Individual seat credits give each user their own allocation with no sharing allowed, which works better when people run genuinely separate workflows: a product manager, a UX researcher, and a designer each running their own study don't need to worry about someone else's usage eating into theirs. Usage add-ons, where credits get bought separately from seats, add friction by splitting the access decision from the consumption decision, forcing a second purchase conversation just to keep using a feature. Neither model scales the way pooling does, and that's exactly why pooling won the packaging argument, not because it tested friendliest in a focus group.
The clearest enterprise signal for pooled credits comes from OpenAI's ChatGPT Enterprise and Edu workspaces, which sell a shared credit pool at the contract level. Every user and seat type draws from that same pool, there's no per-seat usage cap by default, and owners or admins apply role-based access control when they need to restrict who can draw what. The plan architecture behind this usually has three pieces: a recurring charge, whether that's a flat platform fee or a platform fee plus a per-seat add-on, that buys access and seeds the pool; a pool size fixed at the subscription tier; and some overage or top-up path for when the pool runs dry. Companies including Miro and Airtable have been rethinking their own seat-and-usage bundling along roughly this line.
The pooling decision: shared balance versus per-seat allocation and what each signals to the buyer
Shared pools work best when a team's usage is lumpy rather than smooth. Picture a fintech team that spends three weeks hammering on an onboarding flow, goes quiet for a month while the rest of the org catches up, then spins up again to recruit enterprise buyers for a pricing study. A seat subscription priced for the busy stretch overcharges during the quiet one, while a shared pool absorbs that rhythm without anyone having to think about it.
Per-seat allocation only earns its keep when team members work independently and in parallel, and that's a narrower case than most pricing teams assume. A product manager, a UX researcher, and a designer running three separate studies in the same week don't want to compete for one shared balance or trigger a surprise recharge because someone else's project ran long. Give each of them their own allocation and all three work without stepping on each other.
There's a signaling layer here too, and it matters more than it looks. A shared pool tells the buyer this is a team tool built for collaborative value. Per-seat allocation tells the buyer this is about individual ownership and accountability, which procurement teams tend to like a lot more than marketing does. Finance wants to assign AI spend to departments for chargeback purposes, and a single opaque shared pool makes that assignment impossible. That's often the exact thing that pushes enterprise buyers toward per-seat or sub-pool structures instead, no matter how well the shared pool tests with end users.
Hybrid approaches split the difference, and the right default is pooling with guardrails, not treating the two models as coequal choices to weigh evenly every time. One version guarantees each seat a credit floor it can always draw on, with a shared pool sitting on top for overflow. Another carves the master account balance into sub-pools by team, department, or cost center. Either way, this decision isn't just a backend mechanic: it shapes how the pricing page reads and how the sales team pitches the deal. Shared pools are easier to explain and easier to sell. Per-seat allocations are easier to audit, and a lot easier to defend to a finance team asking where the AI budget actually went.
Rollover mechanics and how they shift credit packages from a cost to an asset
Without rollover, unused credits vanish at the end of the billing period. The customer paid for value they never got, and the vendor eats the reputational cost once that math becomes obvious. With rollover, unused credits carry into the next period, and that single change flips the mental model: the credit balance stops feeling like a countdown timer and starts feeling like something the customer owns. Any credit system that skips rollover entirely is optimizing for short-term margin capture over the trust that makes renewal easy, and that tradeoff shows up in the churn numbers eventually, not right away.
Clay's approach is worth studying here. Unused credits roll over month to month, up to a cap of 2x the monthly allotment. That structure works as both a customer-friendly gesture and a lock-in mechanism at once: the bigger the balance a customer builds up, the more expensive it feels to walk away and start over somewhere else.
The cap is what makes any of this workable for the vendor. Uncapped rollover puts unlimited liability on the books, since every unused credit is a future cost the company still owes. A cap set at 2x, or wherever the vendor lands, bounds that liability while still letting the company make the customer-friendly pitch. Caps can also scale by plan tier, so the higher tiers earn more rollover headroom, which becomes a built-in upsell argument on its own.
In team settings, rollover builds up at the account level, not per seat, so a shared pool can accumulate a large surplus that gets drawn down unevenly by whoever happens to be busiest that month. That balance needs to stay visible, not buried in a settings page nobody checks. Clay also offers an alternative worth noting: annual credit grants, delivered upfront with a roughly 10% discount, so the customer holds the whole year's credits at once and paces itself. Rollover carries a second, quieter function too: an account that consistently rolls over a large unused balance is telling the vendor it's over-packaged for its actual usage. That's not just a customer-happiness question. It's a flag for downsell risk, or a chance to have a right-sizing conversation before the customer has it without you.
Allocation controls, RBAC, and making credits governable across roles and cost centers
A shared pool with no governance layer is a free-for-all. Any user can drain the whole balance, nobody's accountable for it, and finance has no way to assign that spend to a department. That's the gap role-based access control is built to close, and shipping pooled credits without it means shipping half a product, whatever the release notes claim.
RBAC lets an owner or admin set usage permissions at the seat or role level: some roles get full access to the pool, others get capped draws, and some get access to specific features only. OpenAI's ChatGPT Enterprise runs on exactly this model, with no per-seat cap by default but full RBAC available to admins who want to restrict access.
Sub-pool allocation takes this a step further by letting an account admin divide the master pool so that one team can't quietly eat into another's allocation without an admin stepping in. This is the direct answer to the chargeback problem: finance can look at the account and see exactly what engineering spent versus marketing versus customer success, instead of one undifferentiated number.
Seat types add another layer of pricing flexibility. A full seat, a view-only seat, and a collaborator seat can each carry a different credit draw rate, which lets a vendor price differentiated access without inventing a new plan for every permutation. For enterprise deals, this governance layer isn't optional, whatever the sales deck implies. Procurement teams treat RBAC and sub-pool support as a checklist item, and a vendor missing either one gets disqualified before the technical evaluation even starts.
Underneath all of it sits a billing infrastructure problem that's easy to underestimate: tracking sub-pools, per-role draw limits, and account-level rollover all at once means metering multiple overlapping credit ledgers in real time. Platforms like Flexprice are built specifically for this kind of consumption metering across tokens, credits, and hybrid subscription-plus-usage models. That's a different engineering problem than the one subscription billing tools were originally built to solve, and teams that treat it as a minor extension of existing billing code tend to find out otherwise mid-migration.
Overage design and why the wrong default creates churn instead of expansion
Credit opacity is the single biggest objection buyers raise about credit-based pricing. Users stop engaging with a product because they can't tell how fast their balance is disappearing, and enterprise buyers push back hard on AI line items unless those items are capped or flat. Get the overage design wrong and it doesn't just annoy people, it actively works against the adoption the credit model was supposed to drive.
A hard stop when the pool runs out protects the vendor's margin, but it kills momentum at exactly the wrong moment: a team mid-project loses access without warning, blames the product for the interruption, and the account is now at risk. Automatic overage billing solves the momentum problem but creates a different one, bill shock, which might be the single most reliable way to sour an enterprise buyer on credit pricing for good. A team that never understood its own burn rate suddenly finds an unexpected line item on the invoice, and the renewal conversation starts from a defensive crouch.
Neither default is acceptable, and treating them as a tradeoff to balance misses the point. What actually works is a third layer that prevents both failure modes at once, not a compromise between them. Pre-depletion alerts at escalating thresholds give admins a chance to act before anyone hits a wall. Cost previews, showing the credit cost of an action before a user commits to it, give users transparency and reduce surprise consumption. Soft overage with explicit opt-in, where hitting the ceiling triggers a prompt for the admin to approve more credits rather than an automatic charge or a hard stop, keeps the customer in control of the decision. Real-time usage dashboards, visible to admins and end users both, remove the surprise entirely by letting people watch consumption happen instead of finding out about it after the fact.
Handled this way, hitting the pool ceiling stops being a failure state and becomes the clearest upsell signal a sales team ever gets. A team that keeps bumping against its limit is telling the vendor it's ready to pay for more, and a clean path to a bigger plan or a one-time top-up turns that friction directly into expansion revenue. None of this erases the margin conversation, though. Revenera's Monetization Monitor 2026 Outlook found that 70% of AI product leaders struggle with delivery costs, particularly cloud spend, a reminder that a forgiving overage experience still has to sit on top of pricing that protects the gross margin floor, a floor that AI vendors must define based on their own cost structure.
Plan tiers, credit packaging sizes, and calibrating the pool to actual team usage patterns
Credit tiers should come from usage data, not a guess made in a pricing meeting, and shipping a tier before that data exists is the single most common packaging mistake in this category. Most companies need several months of real consumption data before they can size a tier that actually reflects how teams use the product. Skip that step and the result is one of two failures: overprovisioned pools that quietly erode margin, or underprovisioned ones that trigger churn the first time a team hits the ceiling.
Usage in team settings skews hard: a small share of power users typically accounts for a disproportionate share of total consumption, which is the exact reason individual credit buckets fail for teams while shared pools tend to work. Size the tier around an average user instead of that skew, and the pool will feel wrong to almost everyone on the account.
A few principles hold up across most tier designs. Pool size should scale with seat count, but not in a straight line, since larger teams carry more usage variance and generally need a lower per-seat credit ratio than small ones. The entry-level paid tier should be sized around a realistic single-team use case, not a single user's usage multiplied blindly by seat count. And each step up in tier needs to deliver a real jump in pool size, not a marginal nudge, or the upgrade won't feel worth the extra spend.
The gross margin floor is the hard constraint underneath all of this: at maximum consumption within a given tier, margins need to hold above the target range for AI products, meaning a pool that looks generous on the pricing page has to survive the unit economics test before it ships. The hybrid structure underneath makes this possible by separating the access charge, the subscription that covers seat count and platform access, from the consumption charge, the credits that cover actual AI feature usage. The access charge stabilizes revenue. The credit pool is where margin discipline actually lives.
Clay's packaging is a useful reference point here: every plan includes unlimited seats, credits are the only real expansion lever, and a modest annual discount paired with upfront credit delivery rewards commitment without forcing a big price gap between monthly and annual. By mid-2026, the market seems to have converged on a two-layer structure worth naming directly: a seat- or subscription-shaped layer on top, which is what customers actually budget against, sitting over a token or compute-metered settlement layer underneath, which is what determines real cost-to-serve. The credit pool is the interface between those two layers, and getting that interface right is most of the design problem covered above.
Migrating existing seat-only accounts to a credit-enabled model without triggering churn
The first rule of any credit migration is simple: don't flip the whole customer base at once, and any migration plan that starts with a full cutover date is the wrong plan from the outset. Launch the credit model with new customers first, watch how it performs, and migrate existing accounts gradually once the pool sizes are proven.
That migration can't happen without data, either. Sizing a credit pool for accounts nobody has measured is a guess dressed up as a plan. API calls, feature usage, AI actions completed, whatever the actual usage signal is, needs to run for several months before the new model goes live for existing customers.
The lowest-disruption path is layering, not replacing: add credit-based consumption on top of an existing subscription instead of tearing up the old contract. Existing customers experience this as new capability showing up, not as a renegotiation of what they already agreed to pay. Bundling an initial credit allowance into the current plan softens the change even further, since the customer sees more value before they see any new complexity.
Grandfathering matters more than most teams expect. Abrupt pricing changes erode trust faster than almost anything else a vendor can do, so customers on legacy plans who haven't been migrated yet should keep their existing terms until a natural renewal point comes around, not before. For accounts in transition, a hybrid structure, a fixed base fee often set lower than the old subscription, plus credit-based consumption for AI usage, lets the customer keep some cost predictability while the vendor moves toward a model that actually captures the value of heavier usage.
None of this lands, though, if the message never reaches the right person. Admins are the ones making the renewal decision and defending the product internally, so migration communication needs to explain pooling, rollover, and overage mechanics in plain terms, aimed squarely at them, not buried in a changelog nobody on the team ever opens.